A heads up that some of your money – if you have this kind of money – will stop being legal tender:
Some Canadian bills are losing their legal tender status from the Bank of Canada at the end of this year. So you won’t be able to take them to the bank or use them in stores anymore. But no worries – tiny odds you even have them. And if you do, they’re worth way more than you think!
The one and two dollar bills stopped being issued in 1989 and 1996 respectively. You may still have some, but they’re too much of a cheap souvenir to turn them in. Your kids or grandkids will love to get them from you.
The $25 note has only 1,840 left out in the world. Rare always equals expensive so a reputable collector will give you way more than face value.
Did you know Canada had a $500 note? Who knew? I think it was only issued one year in the 1930s. But get this: There are only 40 left out there. The Bank of Canada obviously knows how many it printed and how many came back from Canadas’ banks out of circulation. THAT is rare. A very good quality one without stains or marks is worth $50,000. THAT is a big return if one of your grandparents could afford to get it and keep it.
Lastly, the $1,000 bill won’t be legal tender anymore. Those I have seen. I don’t have one, but it’d be a great Christmas present if someone is still wondering what to get me. They’re not rare – there are 632,000 of them still out there. A very good condition one is worth 20 to 30% more than face value. But for all of them, if you find any of them after the New Year and do want to just cash them in, the Bank of Canada will still honour the, but you’ll have to mail them directly to them.
While those bills are going away, the new $100 bill is less likely to be accepted by vast numbers of businesses. There have been over 11,000 fake ones caught in 2018 so businesses aren’t accepting them. Weren’t the new bills supposed to be almost counterfeit proof?
If you’re concerned about the stock market performance because of the US election, here’s something you should know:
Since 1945, the broad S&P 500 has had annual returns of:
6.9% when there has been a Republican president
11.2% when there has been a Democratic president in the White House
A Joe Biden win, along with Democrats controlling the Senate may be a much bigger market bump. After all, there still isn’t a stimulus for tens of millions of Americans – in spite of all the talks.
As always, Florida is always one of the States to watch. Florida’s Governor has fully re-opened the economy to help Trump. Restaurants actually have to apply to the government if they want to open at less than 100% capacity. He also has lifted the halt on evictions effective November 1st. It’s estimated over 100,000 people will be evicted three days before the election. The State has over 1 million Puerto Ricans since hurricane Maria in 2017. They remember Trump’s trashing of the island and his “help” in throwing out paper towels.
Florida relies almost entirely on tourism income since there’s no State income tax, and property taxes are pretty moderate. That’s down over 55% and Disney just laid off another 28,000 workers in Orlando. It’s also a State where half the population is over age 50. And that voting block takes the virus pandemic seriously – very seriously.
The pandemic first hit the coastal areas, then the sunbelt this summer. It is now in the mid-west and Florida. The exact States that were Trump wins in 2016 are now getting hard hit by outbreaks way above the national average. With Florida’s fully reopened economy, along with Iowa and Wisconsin, those three States will have massive problems and record cases, along with exploding death cases by next week. For lots of reasons, that’ll make a lot of seniors leery of supporting Trump again this election.
If you want a US election prediction: Watch election night between 6:30 and 7:00 pm Kelowna time. By then, Florida will have been decided because they’re one of the few states that count early votes in advance – starting this week. So they’ll have full results that night of all – literally all – votes.
It’s not likely to be the typical super-close election there. (Remember Bush vs. Gore in 2000?) If Joe Biden wins Florida, there’s over a 98% certainty he will be victorious. So a Florida win and you can go to bed by 7:30pm. Even if he doesn’t, and you’ll need to stay up for another hour or so – he will be elected the 46th President of the United States.
If you’re not a Trump fan, you need to hope for a blow-out election. If you are, you’re certainly hoping it’s close or that Trump wins. Close means Donald Trump Jr. can run for the Republican nomination in 2024. A blow-out will likely wipe out any further political office aspirations for the family. You’ll just have Trump TV by 2021 and his twitter account to follow.
Federal Reserve Chairman Powell called for a stimulus package as the economic recovery is pretty weak and there’s certainly no chance of inflation returning for years. He warned of “dire economic consequences” without another stimulus. That was first thing Tuesday morning.
It immediately boosted the Dow (let’s just use that one index as an example) by over 200 points.
President Trump doesn’t make speeches – he just tweets: At 12:48 pm it was that “I have instructed my representatives to stop negotiating.” In other words: Forget any stimulus. In less than a minute, the Dow dropped over 400 points to be down 200 points.
No stimulus package means no money for airlines, small businesses, or for millions of unemployed through no fault of their own.
But the bummed out market and investors weren’t done yet. And it turns out – neither was Trump: Less than seven hours and many tweets later, Trump had totally reversed himself: His tweet at 7:54 pm was that: “The House and Senate should immediately approve …(a stimulus plan)…Have this money – will sign now!”
Fast forward to the next mornings’ opening of the markets and the Dow was up 400 points in the first half hour. It finished the day up 530.
Three lessons here:
1..You may not be a fan of our Liberal government, but for all its faults, at least here in Canada we have an economic policy plan that lasts longer than 7 hours and 6 minutes at a time.
2..This is a small insight into why it’s next to impossible to actively manage your own investments in the short term.
3..The lack of another round of help to individuals (at least so far) will have an impact on the election – especially in Florida.
And with Florida in mind, I’ll give you my fearless US election predictions next week…
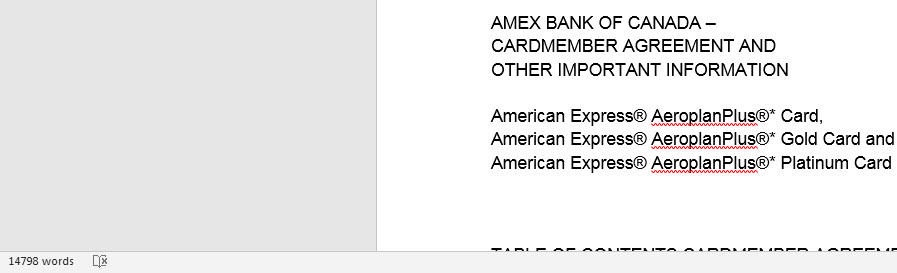
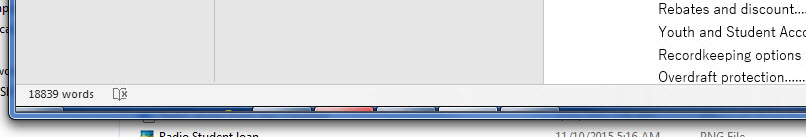
Most every Canadian has at least one credit card or another. Whenever the new card, or any renewal card arrives, it comes with a 14,800 word booklet called the Cardholder Agreement. Yes, it’s almost 15,000 words (see the bottom left for the word count) – about the same as a paperback novel.
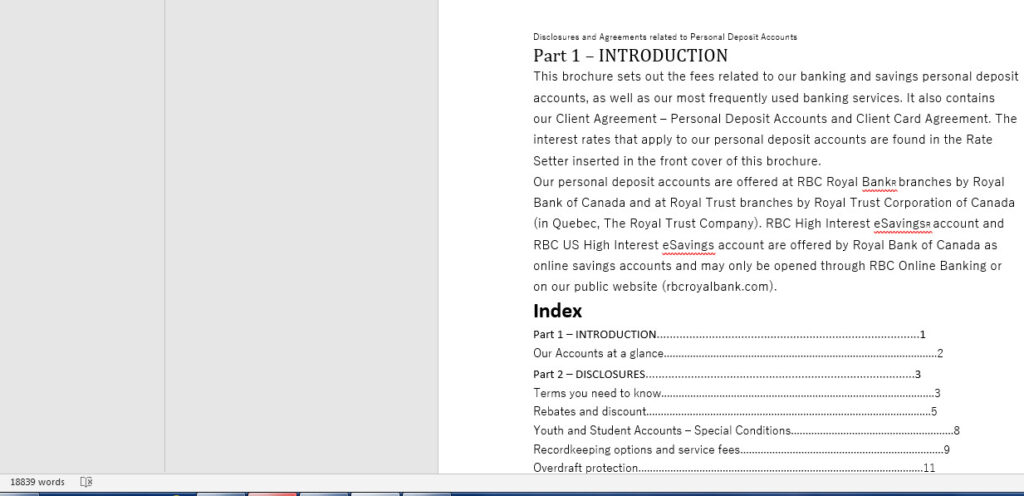
I also just looked through a Royal Bank chequing account disclosure agreement someone sent me. It comes it at just under 19,000 words! (Like credit card agreements, it’s not just this bank, they’re all pretty much the same length and content).
I’m quite sure that maybe one out of a hundred people actually flip through it, or actually read it. The font is so tiny, and the booklet is so thick, that people can be forgiven for just parking the booklet the same place their junk mail goes. And when you open a simple bank account, have you ever seen anyone stand there for an hour or two to read that 19,000 word agreement? Didn’t think so.
However, everything that you have a right to – or actually all the rights you don’t have are outlined in that agreement. So I did what other don’t: I read it and will translate the highlights for you. Mine is from Amex, but they’re pretty much all the same for every card issuer.
For both your bank accounts and credit cards, there are three main things you need to know:
Privacy: Here in Canada, all of our privacy laws apply. However, almost all agreements state that they may use contractors in other countries. That outsourcing means that you agree to be at the mercy of the privacy rules of that country…if they have privacy laws.
Cross collateralization: In your banking agreement, there is always a section that has you agreeing that your bank can use your money on deposit to pay any debts you owe them. If you have a credit card or line of credit and it’s in arrears, you’ve given permission for them to scoop up your money and apply it to what you owe them – no questions asked.
You can’t opt out: With mortgages or loans, you’re actually signing a whole lot of documents for the loan or mortgage. Not so with a credit card. When you get the account agreement, you’re not reading it, then signing it and sending it back. You automatically agree to be bound by all the terms and conditions if you use the card. In other words: Use the card the first time and that binds you to all the terms and conditions.
Other terms that you should know:
PIN number: You’re liable for charges – don’t share it with anyone – ever
Statements: If you don’t get a statement, you still owe a payment no matter what
Charges: You’re on the hook and owe the money. If you have a supplemental card, you’re the only one liable to pay it
Payments: They’re applied in a specific order: First all fees, late charges, etc., then interest, then optional insurances, and lastly to your balance
Who owns the card: It’ll always state that “the card is our property.” In other words, you get the use of it as long as they want you to have it
Privacy exceptions: All of them state that you consent to your information going to third-party suppliers and their agents and their service providers in order to do marketing.
Lost or stolen card: Common sense – contact them immediately. If you contact them within a day or two you’re not liable for any charges after the theft or loss of the card.
Changes: They have the total right to change any terms at any time. Yes, they’ll communicate them to you, but you are deemed to have accepted all the changes from rates to fees to minor things if you continue to use the card.
Default: There are lots of reasons to be in default – starting with arrears. If so, you’ll still be liable for any and all fees, interest, charges, etc., after the card is terminated
Perks: If you have a card with points, miles or whatever, there’ll be a long section outlining those. It’ll always state that these perks are from a third-party (such as Westjet, Aeroplan, Airmiles, etc.) and that they don’t come from your card issuer. They can be ended at any time without notice and it’s not your card issuers’ fault or liability – nor do they have or supply an information on your perks.
Yes, you can still celebrate Christmas on the right day, but you need to know that your wallet can’t!
Traditionally, the big Christmas season sales have been around the week of US Thanksgiving. But that’s going to be much different this year. It’s something you need to adjust to if you’re not in the one-third of the population who leaves it until the last minute. That’s for three main reasons:
Shipping charges: With the huge increase in online shopping, the couriers are super busy already. Fedex doesn’t even have delivery guarantees anymore. Maybe your package will be on time, but most likely, it’ll be days late. What does that mean? Huge surcharges from all the couriers for this Christmas season. It’s an issue of supply and demand. So you need to be very careful when shopping online and check the shipping costs before clicking to buy. It may still be free and the retailer is absorbing it. But you may also see that many retailers are passing some or all of these costs on to you! Buyer beware and read before clicking! It’s also the reason retailers will have sales this October to pull forward a lot of their Christmas sales before the courier surcharges kick in.
Amazon Prime Day: Amazon’s massive Prime day has always been in June. This year it’s going to be in October – and that’s likely going to be a lot of early Christmas shopping on that day. That means other retailers need to adjust, because it’s just that big a deal.
Retailers need the income: Since March, retailers have been badly hurt in their sales – assuming they were even open. If there’s any reason to move up Christmas sales to generate some badly needed cashflow, they’ll be on board. Prime day and avoiding the Christmas season courier surcharges are just three of the reasons.
If your routine is to shop the last week before Christmas, your wallet is going to feel the pain this year!
Both Air Canada and Westjet charge $30 for your first checked bag and $50 for a second one. And just a reminder that Westjet, when this legal rip off fee was first dreamed up and rolled out, stated they wouldn’t be doing that. Well, a few months later – they did…
If you need to check a suitcase, or (like me) bring your golf clubs along) you don’t have a choice. But if you make two flights a year, both airlines now have credit card affiliations that can get you a free checked bag.
Westjet has always had it with the Royal Bank World Elite Mastercard. With Air Canada, it’s on the TD Aeroplan and the CIBC Aerogold card. And now with a number of Amex cards, starting next month! The annual fee for any of these cards is around $100 to $120 a year. However, as you can see online, some will waive the first years’ fee under certain conditions. At two flights a year, you’ll break-even – with three or more flights, you’re ahead, financially. If you do fly enough, check the TD, CIBC, Royal or Amex to see if you have the free bag, or what it’ll cost you to change cards to get something you shouldn’t have to pay for in the first place.
So you’ll excuse me if I’m not a fan of any Westjet or Air Canada government support. They charge a billion plus in legal rip-off fees, are filling the middle seat and still want support. In the U.S. Southwest Airlines still guarantees no middle seat booking and has never charged luggage fees AND they’re profitable!! But that’s another conversation…
Ah, the continuing saga of my new deck continues. Now I’m onto the issue of how to stain, what to use, where to get it, etc. I’ve spent about 10 hours researching this before I finally decided what to buy.
Yes, I’m kind of cheap. Lots of things can be bought at the Dollar Stores and they’re perfectly fine. I’m also good with the Walmart cookies (I love cookies) for $1.50 versus the brand names at five bucks a pop. (Did I mention I love cookies…)
There are other times when it pays to spend the money on quality. The times quality matters and price is secondary is up to you. For my deck stain, quality mattered to me. Not just for the nice look, but I really didn’t want to have to re-do it every year. That likely involves days of stripping the old stain, sanding and stripping off the old stain (or the new one won’t take), cleaning, re-sanding some more, re-cleaning, and hoping that the next stain is a better quality, and lasts a little longer.
I also spent a lot of money on my deck and wanted quality, UV protection, the original look of my deck (I love nothing more than the colour after it has rained) and protection from water and our winters. If I was in doubt about that, my go-to Rona store has two people whose opinions I’d trust. One of them said to me: “Do you really want to cheap out on this?” He was (and is) right: This is one product where you get what you pay for. And “get” the extra work in a year or two if you don’t…
One of my best friends helped me immediately narrow it down to semi-transparent and water based versus oils due to the winds and dust in a new subdivision. That helped immensely. Then it should have been easy to just do a web search for “best semi-transparent deck stain.”
Well, no. But quickly found two great websites: The first one was Consumer Reports. As I don’t have a subscription (and didn’t go to the library to pull the article) I was only able to get the first few basics. The other one was Deck Stain Help. It had very detailed reviews and was easy to navigate. With those two, and a bunch of others, I was able to get a pretty good list of the quality ones and the ones to avoid.
With reading hundreds of reviews (from both the US and Canada) my personal list (and it’s only that) was: Avoid Thompson’s, avoid a lot of Behr with the exception of Behr Premium (about $10 more than basic – look for the 5077 code that has a longer life and warranty), which Consumer Reports rated really well. But I found that people loved or hated Behr, which had me really confused…
It appeared the really quality products (that I narrowed it down to) are only sold in the US. That means US dollars and a lot of shipping. No, they weren’t on Amazon Canada – and most aren’t on Amazon US either.
Then came a problem we’ve talked about before with respect to rating sites. Careful that they are not paid sites where ratings aren’t independent. They’re based on the company PAYING to be highly rated! And that’s when I found that the great review site of Deck Stain Help is actually a website owned and/or operated by the two or three brands they rated highest and reviewed extensively! It’s something I should have caught earlier since the review of the Behr Premium” is listed as the worst deck stain. That doesn’t make sense when Consumer Report shows them as one of the top rated! (See their section on: “Top 6 Deck Stain Reviews”
Darn! It was the “Restore A Deck” product I wanted. It can be applied wet, one coat for new wood only, and easy to apply. So I had to go back to find “real” reviews. Fortunately there were lots on Amazon that are always from “verified purchasers” so you know you’re getting the real scoop!
That was enough to get the feedback to still order the Restore A Deck products. Restore-a-deck.com – ordered two gallons ($40 each of the semi-transparent natural colour stain (other colours are available) and the $50 small combo pack 300 of cleaner and brightener to prep the deck – add UPS ground charges of $58 plus taxes, and the total was just under US$200.
After 10 hours of research, it’ll now be two weeks of waiting for UPS. I’ll post an update when I’ve applied it in the spring.
One more heads up: Whatever stain you buy, you need to assure you follow the instructions to the letter. In 10 plus hours of reading reviews, I didn’t find a single person with a problem or nightmare who even had the manufacture acknowledge the problem. I’m quite sure it’s an industry with zero refunds! Every single problem posts’ response was the they must have done it wrong and/or not followed the instructions!
The first week in March, the markets plummeted. When we talked on March 6th I indicated not to worry, they’d be up 15% again within six months.
In fact, the week after that brought Black Monday, as traders have termed it. The markets tanked again – and a lot worse – with the Dow having its largest one-day drop in history (1,800 points).
Fast forward to yesterday (September 1st) since the over-reaction is behind us and last week all markets have recovered their losses for the year, and have all set new all-time highs. I only talk about investing twice a year and in broad terms. That’s not my degree. But I am an interested spectator because I manage a seven-figure investment for a relative. It’s up 15% for the year so far, because 70% is invested in tech related mutual funds. One thing I can’t tell you about is the Canadian market. The investment firm handling the account has not invested in commodity heavy Canada for over six years.
March 3rd: Dow 25917 S&P500 3023 NASDAQ 8738
March 9th: Dow 18200 S&P500 2191 NASDAQ 6631
Sept. 1st: Dow 28645 (up 57%) S&P 500 3526 (up 61%) and the tech-heavy NASDAQ 11939 (up 80%)
Yes, the 75% NASDAQ rally in August was Apple, Facebook and Amazon while other companies were getting wiped out…but that’s the reason I would never manage my own investments and you always need to have a diversified portfolio. The flavour of the month might not be the same one as next month or next year!
History will always repeat itself. When we see such massive drops in our investments, our mind tends to think it’ll go on forever. Now, with 20-20 hindsight, just as every market correction ever, we can look back at our March investments with a different mindset: The market always bounces back – especially when it overreacts.
The people who have not recovered – and may never recover are those who gave up and cashed out. It guaranteed that they locked in their losses. It’s done by millions of small investors in every major meltdown. They were there for the down rollercoaster and got off at the bottom, forgetting that the investment roller coaster always goes up – way higher than the bottom at which they cashed out.
Do remember that investing is a time horizon of five years or more. If you need the money in less time, you need to save and not invest – that’s a basic savings account or GIC and not the market.
The investments I oversee are in a managed portfolio with a national firm. There have been some hits and certainly some misses:
Pimco monthly income fund has been a horrific underperformer for years. Yet, the firm is adding more of it. Conservative portfolios need a fixed income percentage – I’m guessing Pimco is the best of the worst at these historically low rates.
The firm purchased a gold ETF on May 1st (Ishare SP/TSX GL GLD ETF) but sold it a month later at a $16,000 loss! Six weeks later, with Gold setting new highs week after week it would have been a $26,000 gain! That’s a difference of $42,000. The firm didn’t respond to questions from me. NOT happy at all!
In 2019 the market went nuts in the first quarter of the year. Yet the investment firm sat on the sidelines and did nothing. They’ve since admitted that they “missed” that huge wave…not good, but at least they owned up to it…
On the “win” side, Dynamic ACTV GLB DIV ETF is up over 28% for the year and it’s been a holding for some time, along with a NASDAQ index fund (there are many of them in either Canadian or US dollars)
Those examples show, once again, that even the professionals don’t have all the answers and don’t always get it right.
Next week we’ll wrap it up with some basic ideas on what’s next for the markets and if you should get out…(you shouldn’t…)
Mortgage deferrals this spring: It’s nice to know that many times our Wednesday stories are ahead of others talking about it. May 6th we talked about a heads up that you need to check your credit bureau if you had a deferral on your mortgage or line of credit. BNN finally had it on their website August 13th – three months after us. To make sure your deferral hasn’t shown up on your credit report as arrears, go to Equifax.ca for the form to get your free report or it’s in the Money Tools book chapter on credit reports.
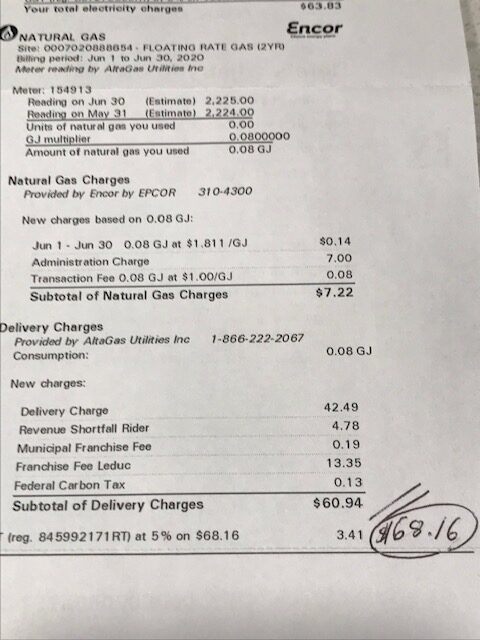
Solar panel payback: Last year we talked about the cost versus savings of adding solar panels to your house. It might be great for the environment, but it’s horrible for your wallet. The savings will only be your actual energy consumption cost. You will still have all the fees on your bill. Here is my last utility bill as an example. My actual gas cost was 14 cents. I know it’s summer, but even a really low $10,000 solar install will save me 14 cents a year, or around $50 in the winter. The other seven charges were over $67 and you’d pay no matter what.
Car rental reminder: If you didn’t hear it last year, this is your reminder: It may be weeks later after you return your car that you’ll get a bill for damages to your rental. It will be a bill in the mail or they may already have charged your credit card. All rental agreements state that it’s subject to final inspection. Many times, especially at airport rentals, you just hand in the keys and they never look at the returned car at the time. That’s happening more and more as you can see on travel blogs. So take pictures, it’s digital so it’s easy to do. One of the windshield, and one each side, front and back! That way you’re protected…just in case…
Teaching kids about money: We talk about this at least once a year. Here’s a beautiful reminder that kids DO understand if there’s financial trouble. If Mom or Dad are off work because of the covid pandemic, you can, should – actually must – talk to your kids about it. Make it age appropriate, but do make it a conversation. This beautiful note is from one boy for his Mom.
I’ve had frequent feedback on my $39 cell plan. Likely from people who are around the $100 a month mark on theirs. Mine is FIDO with talk, text and very little data. (New customers and plans start around $45 a month now).
If you want, but I would NOT rush right into it, you may be able to get a free cell phone plan.
There’s a new cell provider – sort of. It’s Shaw Mobile – you may have seen or heard their ads in the last few weeks. Shaw Mobile isn’t actually new – just a new rollout. Shaw purchased Wind mobile in 2016 and re-named it Freedom Mobile with about a million subscribers. Now they are expanding to Shaw Mobile, but appear they will leave Freedom in operation, too.
Shaw’s introductory offer if you’re a Shaw internet customer living in BC or Alberta is a free cell plan with unlimited text and talk. If you want data, it’s $10 per gig and it’s good for 90 days if you don’t use it all each month. If you’re like me and don’t watch movies or endless YouTube clips, that is plenty of data! If you want almost unlimited data, the introductory rate is $45 a month with 25 gig of data.
The bad news:
-If you’re on a contract with someone, you’re not a free agent and are stuck. It’s the reason I keep harping on never signing contracts.
-If you’re not a Shaw internet customer, the offer is $15 a month for talk/text or $85 with 25 gig of data.
-The other bad news is that this is an introductory offer. It won’t last and that’s one of the reason I won’t switch. If the real rates explode, I’d be stuck with a higher rate than I currently have. So I’m going to wait until the real rates show up.
You need to also know a couple of other things:
-The rollout is brand new. There are always bugs and problems. If you need your phone – don’t consider switching until the bugs are solved. And read the review below!
-You must live in BC or Alberta to get the cheap rates.
-The switch to Shaw needs to be made in-person at a Shaw retail store. That means you’ll likely line up for one or two hours! Do NOT leave until you’ve tested your internet and an incoming and outgoing call. There are lots of stories that you’ll need to go to the back of the line if it turns out your phone isn’t working!
-Yes, Shaw sells phones, too, including Iphones and Samsung. But the plan offers are based on bringing your own phone.
-You’ll have a $20 admin fee – which is reasonable for the industry.
-It’ll be 4k (speed) so you’ll have good service if and when everything works.
-All plans come with voicemail and caller ID
The reason Shaw can (maybe) end up with lower cell rates is that they’re already getting a ton of your money from your internet subscription. Plus they have over 100,000 wifi hotspots across the country. If you cell isn’t catching one of those, it’ll automatically switch to Shaw’s LTE network.
Because I do need my phone (as I don’t have a landline) this review, along with not having the real rates yet assures I won’t even consider switching right now:
SHAW MOBILE!!! Don’t switch from your current provider!!! What a disaster! I switched from my mobile company to Shaw mobile. Shaw texts me my first bill @2am – 6 hours after I signed up. My phone keeps switching between nationwide and no service. I talked to a representative after a lengthy hold and was told that this is new and there are some kinks to work out. Could I be patient and wait longer. Are you kidding me? I need my phone to do my job! After no service for over 12 hours I ported my number back to my original carrier. (edited for spelling)