Cutting down returns: We talked last fall, and in March, about retailers looking at ways to drastically cut down returns or exchanges in any way they can. That’s well on the way with Walmart. No more exchanges without a receipt – period. If your meat or fruit is spoiled, or your milk is a so-called leaker – you’re out of luck.
For me it was a package of Walmart branded light bulbs that were the wrong kind. I understand the logic of no receipt-no exchange. But this was Walmarts’ own product. So I wasn’t trying to get one over on them! No chance of an exchange when it was clearly a Walmart only product.
When I buy non consumable stuff, I always keep the receipt. But when it’s only some light bulbs in with $50 of groceries, I throw out the receipt. Don’t do that! If nothing else, keep every receipt in a junk drawer for at least a few weeks – even if you only purchased groceries. Not nice, Walmart!
The US has a money shortage…sort of:
The US has $47 billion of coins in circulation – and that’s in a country that only has quarters or smaller because politics won’t even let them get rid of the dollar bill in favour of a coin. But right now that $47 billion is kind of missing. All that money is at home, in peoples’ cupholders or ashtrays and huge amounts of rolls in stores that are still closed. In other words, they’re not circulating and it’s a huge problem right now for the US Treasury. Kind of strange to think where some of the problems happen when the economy shuts down.
This year, I am the perfect example of someone with the worlds’ worst timing: In mid-January I downsized into a new half-duplex. That was before the world fell off its axis. Started work on my basement right away not knowing what was about to come. I do have to do landscaping as new homes have a holdback (in my case $1,500) that’s only refunded once landscaping is done. And this week I just finished my deck. No, that one wasn’t a necessity, but I’m too anti-social to sit on a chair in front of my house for a year.
So, right now I’m a deck expert until I forget everything in a month or so. But I’ve also realized that I’m pretty stupid in wasting money by being short-sighted, not asking first, or thinking ahead.
On my smart side I started buying treated lumber in April when various sizes I needed went on sale. It saved me about $150 waiting for the odd sale and storing them in my garage.
Then came the money waster. There are two sizes of screws needed: 2 ½ inch for the thin deck boards and 3 ½ inch for the structural stuff. How many could I possibly need? It turns out it was almost 3,100 screws! Who knew? Not me. I bought 200 of each, then another 200, then a hundred, then my contractor told me I’d need 1,200 for the actual deck boards (which I found hard to believe) and so on. In other words, I made at least a dozen trips to buy screws again and again and again. That’s the price I paid for not asking!
Yes, I do hire contractors to do things right. Besides, I have zero knowledge and roughly the same talents. But I always find a solo proprietor that lets me be the helper, which saves me a ton of money. In the case of my deck, did all the structural stuff to make sure it passed the permit inspection – I do all the manual labour like the trim, hauling stuff around, and a day of 1,400 screws into the deck boards…that’s about the extent of my talents anyway…
After I was so proud of my lumber savings, way more than that was wasted not buying 2,000 for $61. I tripped over a dime to pick up a nickel and it cost me over $240. I love my double deck and flared stairs and it turned out great. The total cost was $3,800. But all I can think about is that it should have been almost $300 less…
I am also blessed to have another secret resource: My neighbour Greg. He is as nice as he is talented, with everything from heating to (future dream) air conditioning how-to’s, landscaping issues, and construction knowledge. Greg also has tools – adult tools. A lot of adult tools! Metal saws (now learned they’re called grinders), a compressor that saved me countless hours using a Brad nailer, and screw drivers that last for days (my baby one last for two hours before a long recharging time-out). Oh, and a Jeep with a hook and a chain when my 250+ pound tree rolled into its four foot hole horizontally…but I don’t want to re-live that…Plus, he’s incredibly generous with my stupid questions and total lack of building IQ – and all for the low price of just asking and the odd bottle of Bailey’s…
Ahhh…lessons learned the expensive way. This December 31st I AM going to stay up until midnight. Not to party, but just to make darn sure that 2020 really does leave!
CMHC reported that the 2019 national apartment vacancy rate was down to 2.2%. Yes, because the stress test does not allow younger people without a big income to buy even an entry level condos or townhouses. Yes, it’s fine to pay triple the amount in rent – but heavens forbid they want to become home owners. Another way the Federal Government, through CMHC has absolutely messed up the free market system. But it does reward landlords with huge rent increases since their renters don’t have the option of purchasing and landlords don’t use a stress-test.
To make things worse, CMHC tightened up the rules even more to put the brakes on home sales in the middle of a no home sales market. Your total payments from credit cards to your car, to the new mortgage, taxes and utilities now can’t exceed 35% of your gross income. That’s down from 39%. So someone making $50,000 just had their ability to get a mortgage reduced by $167 a month. Plus you now need a credit score of 680 or higher – up from 600 and you can no longer borrow the minimum 5% down payment.
The person making $50,000 in our example can have 35% maximum going towards all bills. That’s $1,458 a month. That’s an easy calculation before ever even thinking about becoming a home owner. That has to include taxes (let’s just use $300 a month) and utilities (most lenders us a flat $100). Deduct that $400 from the maximum allowed leaves this person $1,058 for the actual mortgage.
Since it’s most likely to be a condo or townhouse, the condo fees have to be in that 35% maximum debt, too. You’d be hard pressed to find a condo fee under $250. OK, so condo fees, utilities and taxes off the top brings it down to $800 left. Next hurdle is that you need to qualify for a mortgage rate 2% higher than actual. So rough numbers is that you need to do the calculations on about a 5% mortgage rate even though you’ll be under 3% in your actual payment. And that’s a max of $135,000. And don’t forget that this is 35% of all debt. So this math is all assuming the person has no car payments, no student loans and zero balance on their credit card. If it’s someone with a $300 student loan, it’d be a maximum mortgage under $90,000. Or wait until the student loan is paid off in 20-years before every being able to buy a home.
Tell me what you can buy for $135,000 in the Okanagan – or anywhere else for that matter. And tell me what 20 or 30 something is paying under $800 rent for anything other than a garage.
Sure the stress test has a purpose. But that should be to slow down the one million dollar buyers with a 95% mortgage. Instead, it’s the law of unintended consequences of hitting the entry level buyers.
Our Federal deficit will be between $280 and $300 billion this year! The deficit is just what we’re short in spending versus income. No, it’s not like a credit card. That’s a cute political shot that’s just not close to being true but sounds nice and simple. But think of it as you spending more than your income. If it was $500 a month that’s a problem – but that can be solved. Then, overnight, it turns to being short $15,000 a month! When it’s 30x you’re no longer going to find some savings or being able to count on a cost of living raise. You’re starting to wonder if your 14-year old can hold a full-time job or whether you could live in your car…
And this isn’t an abstract problem that’s happening to a neighbour or friend. This is happening to you and me – we’re not just cosigners of this shortfall (and the debt that’ll hit a trillion dollars by the end of the years.) There’s only one group that owes it: You and me.
As a result, the government (this one or the next one) will need some huge extra income. Cutting a bit here and there will help but won’t get one-one hundredth of the money.
It’s a pretty safe bet that the GST will go up. That’s a big pot of money, but won’t make much of a dent. Tax increases? Maybe – but forget the political like that “we can just tax the rich.” It’s bullcrap. There are only 270,000 Canadians earning over a quarter million a year and their marginal tax rate is already over 50%.
Could it be that they’ll start taxing the sale of your home? Your principal residence sale profits aren’t taxed. But it’s a good bet the government will look at it and maybe float that as a “trial idea” within the next few years. Whether it may come to pass or not, start keeping all your receipts for home improvements. If you made $300,000 selling your home it’ll be a big help to have $60,000 in receipts to deduct from that profit before it’s taxed. If it doesn’t come to pass, you can throw the envelope out – but you can’t recreate the receipts a few years from now.
If you have any other ideas of where the government can find a huge untapped pot of funds, I’m sure the finance minister would love to hear from you. Every level of government has their hands so deeply in our pockets already, there just aren’t many places left…
I doubt there are many people who question the wisdom or necessity of the Federal Government help because of the Corona virus. However, a rainy day fund of savings when the economy was humming along would have been great. But just breaking even hasn’t been a priority for years. The next five years will be a huge rude awakening for taxpayers that didn’t care much over the past decade…
With the extension of the Canada Emergency Benefits of $2,000 a month, vast numbers of people (that aren’t back to work) are now able to bridge their income for 24 weeks and a total of $12,000.
This is your 10-months notice that you WILL be paying tax on this money. You do on your earnings, on any EI you collected and on these benefits.
If your total earnings this year will be roughly the same, just take last years’ tax return and divide your total income line by the total tax you owed and/or paid. That’ll give you your tax rate. No matter what, it’ll be 20 to 30%. Since there isn’t tax deducted from your Emergency Benefits, you’ll need to be ready. At 20% that will have you owing at least $2,400 in taxes. With 10 months notice, that’s setting aside $120 every two weeks. If you choose to ignore that oncoming train and wait until January, you’ll need to save $600 a month since you’ll only have four months left before it’s due.
Your choice: $120 now or $600 later. But then, “later” don’t complain that you didn’t see this coming!
The last few months of having the economy pretty much shut down is generally described as ‘inconvenient’ or ‘hard.’ But the people who are making those statements are likely politicians, economists, talking heads on cable news or medical people. Almost to a person, ‘hard or inconvenient’ is how they view it. However, these politicians, economists, TV anchors or medical professionals are all earning over $100,000 a year.
Put yourself in the shoes of someone who earns between minimum wage and maybe $3,500 a month. To them, it’s a nightmare and not just an inconvenience. Where you are on the income scale makes all the difference in how you see and feel and hurt in this pandemic.
The US Bureau of Labour Statistics (used from a CNN podcast this past weekend), which wouldn’t be any different here in Canada, reports that of the top 25% of income earners, over 60% are working from home and getting their paycheques. But in the bottom 25% of income earners less than 10% are able to work from home. THAT is the difference in the mindset and language of someone who is inconvenienced having to work from home but still getting full pay and the lower income 25% who need to GO to work to get paid. Plus, 13% of those over $100,000 have been laid off versus almost 40% of those under $40,000. That’s pretty staggering and changes the situation from hard or inconvenient to devastating and a nightmare.
The lower income 25%, or those earning less than $40,000 are also the largest group of renters. What’s happened to rents over the last 10 years? Rent keeps increasing because of property values, taxes, utilities, etc. going up. The top income earners either don’t have a mortgage or can make a call to their bank and may get deferrals or at least a line of credit to ride out the storm. What do families making under $40,000 do?
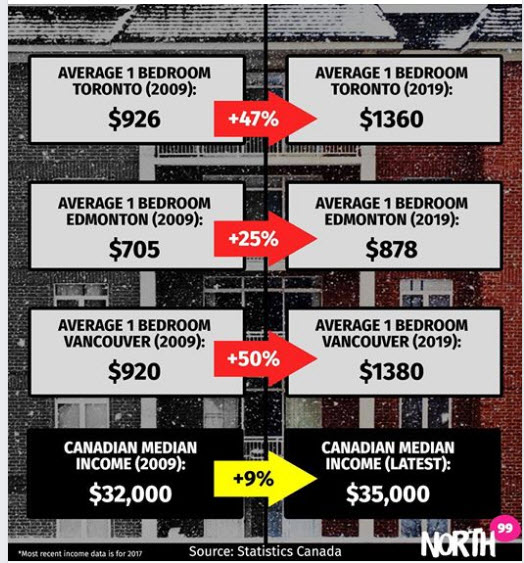
In the last 10 years, according to a report by Statistics Canada, rents in Toronto have gone up 47%. In Vancouver up 50%, and in Edmonton – not exactly a hot real estate market, rents are still up 25%. You know that incomes haven’t even kept up with inflation. So in a so-called good or normal economy the squeeze was already happening. How do you afford a rent increase over double your raise? With borrowed money for the difference – if not a second job. After all, you can only downsize your rental place to a certain point.
I don’t have answers, but if nothing else pay attention to the language you hear being used in an economy worse than the great depression. The perception of how ‘inconvenient’ these times definitely depends on your perception and reality…measured in large part by your income…
Hello George: Thanks for taking the time to read this.
I listen to you on am1150 with Phil Johnson as often as I can. I really enjoy what you have to say.
I really need your advice: I live in Kelowna but sold my place just before the covid19 hit and I have to be out in a few months.
I placed an offer on a townhouse pending mortgage approval. My issue is I just lost my job from c19 and I will have to get a mortgage from the “b” lenders. If they even accept me, will a higher interest kill me? Do I kill the deal and rent? That’s if I can even find an affordable place! It’s crazy out there right now. Any advice would be greatly appreciated. R
Hello, R: Thanks for the note and kind feedback! YIKES! The perfect storm… The great news is that you sold your place and will have money.
I only ever answer questions of what I’d do and don’t have all the details: But this one is easy: RENT RENT RENT
I wouldn’t take on that insane rate AND fees buried in there, and the stress of not having the income. There’ll be tons of other places to buy – don’t sell your soul to do this.
You’re not the only person in this situation, right? So will home values go up or down? Right – so that’s benefit #2.
Will you be back to regular income when you’re less stressed, less in debt, less panicked and under less time constraints? That’s benefits #3-6.
Yes, rent may be so-called ‘wasted’ money, but it buys you peace of mind and no hassles, no 7-10% interest rate, and a BIG penalty to get out of it AND maybe $1k to $2,000 in fees in there.
You need a real lender, and not one that’s taking advantage of you and that can’t happen with no income right now – period. Rates aren’t going anywhere until next year at the earliest, so there’s no rush – no downside – and only benefits to waiting.
IF you can afford it, consider getting your realtor to just ask the buyer if they’d like to move out the possession. The sale is still valid and legal and binding – just changes how long you can stay in there, OR maybe they aren’t fixed on moving right in and will rent it back to you for 90 days? Doesn’t cost or hurt to ask…
Does that give you something to mull? Keep your head up, your stress down and your priorities straight!
Banks
started offering payment deferrals about a month ago, and it’s now over half a
million who have done so – and that’s just mortgage payments. But there may be
a problem, especially for the early applicants: It may have destroyed your
credit rating.
But
let’s back up a minute first. There are two credit bureaus in Canada. TransUnion
and Equifax. Unfortunately Equifax has 90% of the business and is the primary
source for almost everyone but Scotia. They’re just a really horrible company
for lots of reasons. But both credit bureaus, when the thought of extensions
started immediately called on the banks to set up the correct coding for these
extensions. But the banks were slow to get this done.
If
our listeners had only a one number code to rate the segment, it might be 1 for
great, 2 for boring, 3 for make George go away, or 4 for average. That’s it –
four codes. That’s how the credit bureau does things. But a deferral didn’t
have a code set up. So a ton of the first deferrals went through as unpaid –
which means behind in payments – which means a huge drop in your credit score
until the banks reported the deferrals with a new code.
The
how to check your files is in the credit burau chapter of the Money Tools book.
Just go online to Mosaic or yourmoneybook.com if you don’t have a copy.
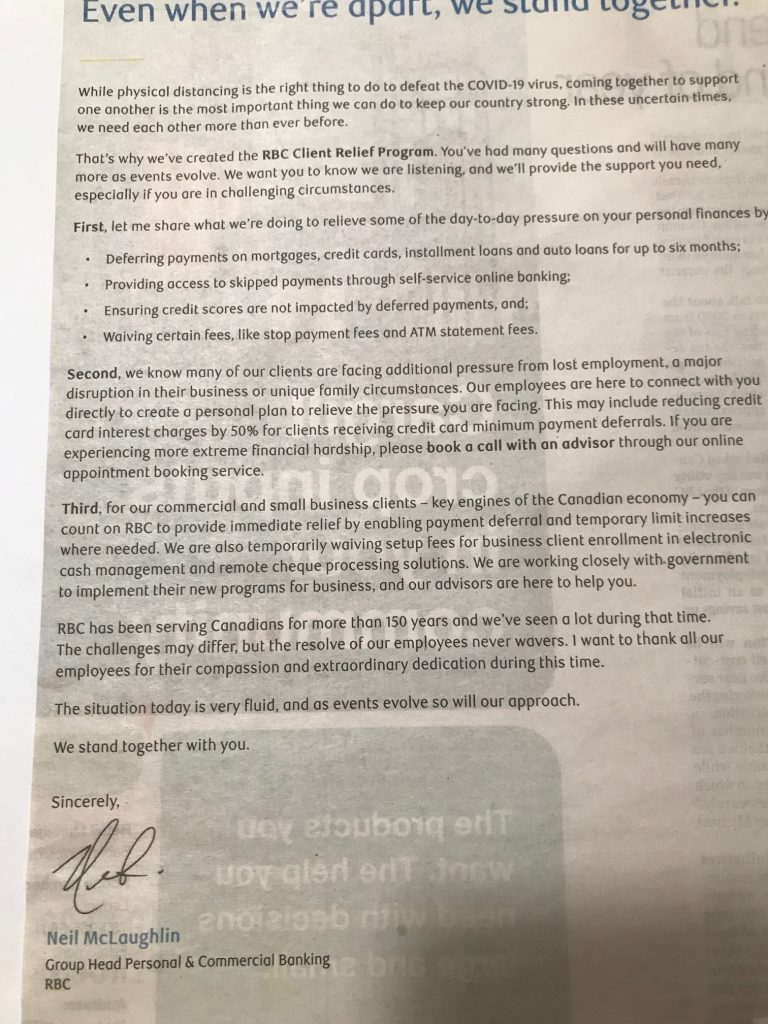
If you’re impacted, it’s obvious that you need to get this corrected – and that could be a part-time job. If you deal with the Royal, their Canadian President had an ad in newspapers across Canada the first week in April. In there, it stated that they will “ensure credit scores are not impacted by deferred payments.” Here is the full ad:
If
yours was, here is the contact information for the President who wrote the ad:
Neil McLaughlin, Group Head – Personal & Commercial Banking 200 Bay Street, PO Box 1, Royal Bank Plaza Toronto, ON M5J 2J5 Phone: 888 212 5533 (your odds are zero of even reaching his EA, though and you want your issue in writing anyway) Fax: 416 955 7800
If
your credit report problem is not with the Royal, you’ll need to do some online
searches for their head office and/or a Regional VP and an address.
And
here is a form letter that you can use. Search under radio stories to get the
information on how to complain effectively that we talked about a few months
ago. Keep it simple, keep it short, factual, and state what you want to
achieve. And always always keep every copy of every letter or email and a
record of every call and the time, date and who you spoke to. This is too
critical not to be disciplined!
If
you don’t deal with the Royal, you can use the same letter, just take out the section
referencing their advertisement.
Dear
Sir:
Re:
Incorrect credit reporting of my deferral
Your
bank processed a deferral of my (mortgage/credit card/line of credit/loan)
payment in the month of xxx.
However,
my credit report since that deferral shows it reported by your bank as past
due. That is NOT correct and has to be corrected. As you know, this has a huge
impact on everything from my insurance to interest rates and future borrowing! As
you also know, the credit bureaus (TransUnion and Equifax) cannot fix this
error as (you) the lender has to submit the right reporting information to
them.
Your
national advertisement the first week in April, under your signature, stated
that you were “ensuring credit scores are not impacted by deferred payments…”
I
need to have someone in your office correct the coding from the incorrect “past
due” to the corrected “deferral,” and re-report it to the credit bureaus.
Or
in the alternate supply me with the proper person, their address, and/or email
in your bank that I need to contact to get this corrected immediately.
I
look forward to hearing back from you – thank you in advance,
Yours
truly,
(Your
name)
Address:
Telephone
#:
Branch
you deal with and main account #:
Account
# of deferred credit card, loan, line of credit or mortgage
AND
send or deliver a cc copy of this letter to your branch as well!
Good
morning George! I listen to you every Wednesday and I hope you can help! We
returned from Arizona on March 15th and went into mandatory quarantine. We
addressed a ton of mail after 4 months, during that time my RBC(Westjet)credit card
had renewed and I had numerous letters from RBC concerning payment. Two weeks
ago was the first opportunity to go into my bank to pay the full amount as I
never had my RBC on my online banking.
I
have always had a strong credit rating in the 800’s on my credit score. I was
shocked to see my credit score now was dropped to 721 due to this one bill. I
have spoken to numerous contacts within RBC and all they do is point me to the
credit bureau. Due to their reduced hours/staff I have been unable to get thru
to them. I feel under these circumstances it is really unfair and wondering if
you can assist me in any way. N.B.
Thanks
for the email, N.B. While I understand your disappointment and frustration, reporting
your missed payments to the credit bureau was factual and correct. Yes, there
are always reasons, but you were past due.
It’s
a common question, so let’s go through three things:
Read
the chapter of the Money Tools book on credit reporting, the impact on your
credit score and how to deal with it and/or fix it. A great credit score such
as his, with one past due plummets it by about a hundred points – as N.B. pointed
out. It’ll come back within a couple of years and it’s still good enough to not
impact him that much. I call this a stupid fee: Almost a hundred bucks in late
fees is a reasonably cheap lesson.
You
need to make a minimum payment or 31 days later the lenders’ computer tells the
credit bureau – period. It takes less than 10 seconds to set any bill up
online. Whether it’s travel, missing statement, forgetting, or whatever – none of
that matters. I have a small chart that I use every month with the bill and the
due date. Mortgage 27th, tax 30th, utilities 8th,
Amex 10th, etc. to make sure I never forget – ever.
Now
to what the Royal is telling you, which is that you need to deal with the
credit bureau on this. It’s a big fat lie that every lender from banks to credit
card companies to GMAC, Ford Credit – literally everybody uses. It’s a quick way
to shift blame. It’s a lie. Who told the credit bureau that you were late?
Right – it was the Royal. So they’re telling you to go to the people who just
note down the information and not the people who told them to do it!
In
this case, the Royal Bank computer downloads every card holders information for
the month: The credit limit, balance on your statement, last payment made or
not made and the amount, and whether the account is up to date, a month, two months,
etc. in arrears. The two credit bureaus take the information and file it on your
account that other lenders can now access and see.
When
the Royal told you to call the credit bureau they knew they were lying to you.
But it worked – you went away and tried to contact the bureau. Bad news: The
odds of reaching them are zero – most of their staff is in India and you’re
dealing with companies that don’t care and can’t help you. They didn’t do the
damage as I explained, and you’re not their customer: Their customers are
lenders, landlords, bonding agencies, etc. who purchase their credit reports.
If
there is factually incorrect information on your file, then it’s the credit
bureau who needs to fix it. If you have a car loan on there and you don’t owe
money on a car, if you have a collection showing up that isn’t yours, or stuff
from an identity theft, that is the responsibility of the credit bureau to fix
and/or remove by law. That’s the case for around 25% of files and the reason to
check your report at least every couple of years.
It
was accurately reported by the Royal. The only way to get them to have a heart
and forgive and forget this one mistake is for the Royal to fix their computer.
It can be done if you are a valued client with lots of business with them. Tell
them it’s a one-time error and ask them to remove it or you’ll take your business
elsewhere. In this case, N.B. only has the credit card with the Royal and isn’t
likely to have a chance of getting it removed.
Two
weeks ago we talked about what to do: Getting the family involved, stopping any
savings and investments, and your financial priorities of prescriptions, food,
shelter, utilities, basic clothing and transportation.
However,
the reality of $4,000 in bills on $2,000 of income brings up three big “should
you” questions:
Should
you pay minimum payments on your credit cards? If you can – absolutely. If you
have the available credit, I would also take a cash advance then use that money
to make the minimum payment. It’s not a solution, but it’s a way to tread water
and protect your credit rating. If you can’t – plan B may be to ask the card
issuer for a deferral, but that depends on how much the minimum payment is,
whether you’re prepared to go through the qualifying again on the phone, and
your priorities.
Should
you get some money out of your investments or Tax Free Savings Account? Yes –
if that’s what it takes to make minimum payments for some of your debts. It’s
better to borrow from your future self than a deferral that just stalls things
off and compounds interest.
Should
you cash some RRSPs? That’s different than other investments, because there are
big tax implications next April since it’s considered taxable income for 2020.
If you have absolutely no choice – the answer is clear. If you can avoid it for
at least another month or so – that would be even better…
There
is a really important chapter in the Money Tools book called “Today’s problems
become tomorrow’s nightmare.” Before you cash any of these, you really really
need to read that chapter.
When
you need to relieve the today pressure with tomorrow money, there’s a steep price
to pay down the road. Cashing any investments relieves the financial pressure
today but leaves you in trouble down the road. Not investing right now is
totally logical, but cashing out requires you to remember that the $5,000 today
isn’t growing anymore for retirement. That $5,000 today, if left alone, turns
into $40,000 that you do not have in 21 to 25 years when you may really need
it.
Secondly,
the government programs of the $500 a week or your EI are fully taxable. So the
today help is great, but you will need to pay tax on that come next April. No,
you probably can’t set aside the 20 to 25% you’ll need for tax today. But you
also can’t claim that it’s a surprise you’ll have to have the money to pay your
taxes.
Lastly, something a little more hopeful if you have a mailbox. I found a great picture that might prevent you from getting more bills that you don’t really need right now. Oh if only that would work….