
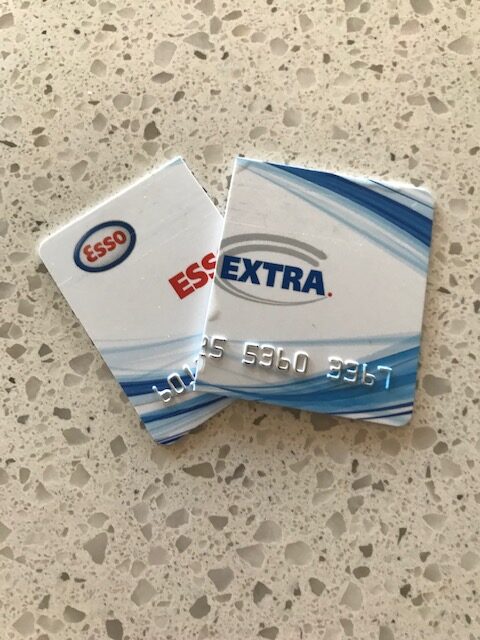
Add Esso to the retailers who have moved up their reward earnings needed this past month. After five years or so, I had enough points for a $50 gift card that I redeemed. But also had another 1,200 points. At 1,400 it was going to get me another $10 gift card before cancelling the card.
Nope – a $10 gift card now needs 1,800 points. As the closest Esso station is almost always 2 cents higher than anyone else. To get the 600 points, I’d have to spend $600 in fill-ups. But that requires overpaying 2c or $12 to get $10. Or overpay about 7 cents on average over the Costco gas bar five km down the road. That’d need $40 overspending to get $10.
Good bye Esso Extra – not going to miss you.
In a week when the Edmonton Oilers play the Canucks four times and may well lose all four, maybe I have something that cheers up Canucks fans. Or makes them feel a little better about their team.
Part of Money 101 is pretty easy: Don’t get into bills that you can’t pay – don’t write cheques when you don’t have the money in your account. You’d think that’s pretty basic common sense.
When NHL teams are on the road they stay in 4 or 5 star hotels. Not bad to be in $200 to $300 rooms. In Dallas, a number of teams, including the Edmonton Oilers, stay at the Crescent Court. It’s in a very upscale area of Dallas called UpTown, with a discounted rate of US$261 or so.
That was the case for an Edmonton road trip December 16, 2019 with a bill of $28,000. Then again after another away game in Dallas March 3rd of 2020 for another $27,000 hotel bill. The good news was that the Oilers won the game that night (2-1). The bad news was that the team bounced the cheque to pay the December hotel bill.
To make matters worse, the Crescent Court hotel then didn’t get that bounced cheque (or thus the actual bill) paid for 11 more months, and never did get paid for the March bill just before the start of the pandemic and NHL shut-down. I suppose I have to keep saying “allegedly,” even though court filings are accurate, because lawyers can’t lie in court and court documents.

Yes, the hotel finally had enough and sued the Edmonton Oilers in court for the outstanding US$55,000 in November. That’s over a year after the first bill – not good. The matter has now been “settled.” I’m guessing settled should just mean “paid in full.” Plus, add the Oilers to the long list of businesses using the pandemic as an excuse for bad behaviour. “We face the same challenges as any business in the midst of a global pandemic.” That was the statement from the team. FYI: the unpaid bill was November 2019. That was four months before the pandemic.
A company with owner Daryl Katz (living in Vancouver by the way) who is worth $3.5 billion (according to Forbes) shouldn’t have this in the media. They should also have a better accountant, and an overdraft, or a bank that trusts them enough to cover the cheque even if that account is short. There are definitely more questions than answers here.
Conner McDavid is the Oilers captain. So I’d suggest he does the check-out at the hotels on his credit card. He’s responsible and reliable. That way the bill gets paid, and I’m sure the Oilers will reimburse him within days not months. Plus, he makes enough income to get the Amex Black Card with literally unlimited spending to make sure the charges on a long road trip go through. Sure, it’s a $7,500 first year annual fee – but it’d be a win win: He gets massive points and the Oilers get a massive reputational boost.
Wow, you’d think that after 15 years and almost 700 of our radio segments we’d have talked about everything by now. Not true – not even close – never in the world of money and finance!
Pop quiz: Is hiring a company for a $20,000 job to finish your basement considered a home improvement? Nope – probably not.
Is buying gum and hand cream at Lowe’s considered a home improvement purchase? Yup.
See – and you thought you knew!
On Monday, the Royal Bank Westjet MasterCard (MC) started a double points (Westjet dollars) promotion on “eligible” electronics and home improvement purchases. Just after I bought $200 of treated lumber – it never fails…
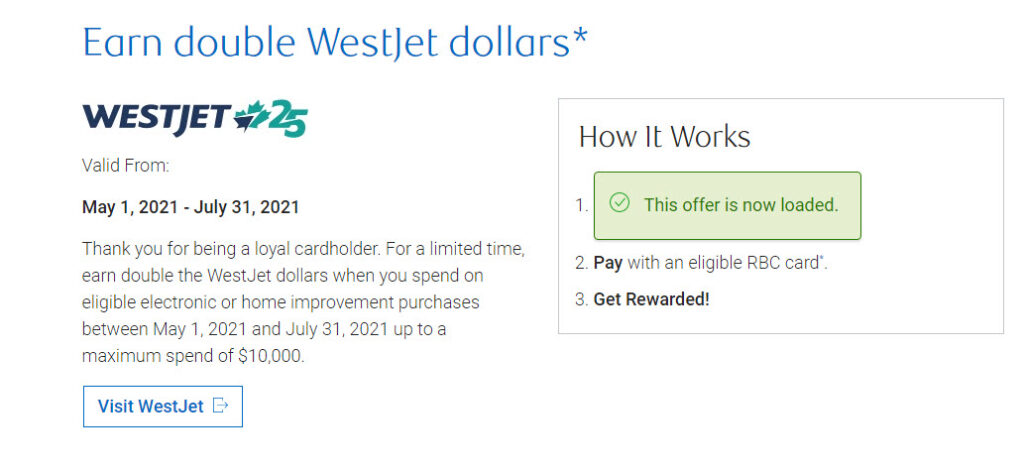
Almost every card will have these promotions from time to time. But it’s buyer beware because the key word is “eligible” purchases. The hundreds of thousands of retailers and companies who accept credit cards all have a merchant category code (MCC) that identifies their primary type of business. My company is consulting – so it’s coded as professional services. That’s the same for accountants, dentists and the likes. So if you buy some lumber from your lawyer, or an “I love George Wednesday mornings” T-shirt, it’s still a charge in the category of professional services and not home improvements or clothing.
It is not what you buy that matters. It’s a charge in the right category that determines whether you get your bonus points for any promotion. A contractor won’t be coded correctly so your $20,000 charge won’t get you bonus points. But Home Depot, Lowe’s, Rona, Home Hardware, General Paint, or the likes are always coded home improvements. So whether you buy gum, lumber, paint, or appliances there, you’ll get the points.
Here is the full disclosure on the bonus point offer. It took me almost half an hour and comes from three different places. Thank you Royal for the details, but would you look a half hour to find these when your card offers them?
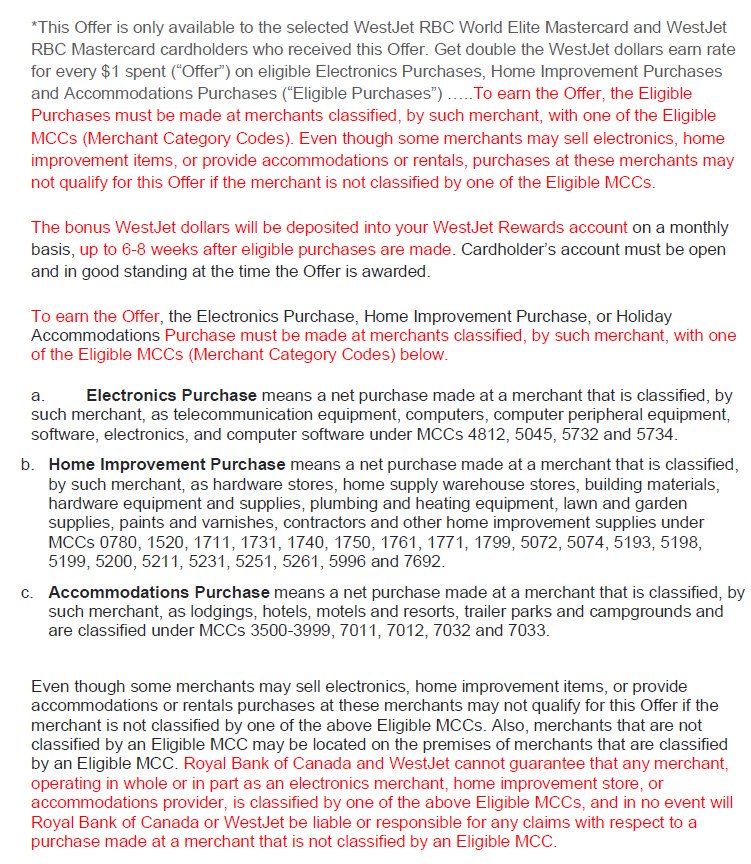
-Your bonus points won’t show up on your statement for 6 to 8 weeks. By that time, any promotion is probably over and you won’t know if you actually got them.
-You can’t get the MCC code in advance to know if you’re buying the right stuff from the right merchant with the right code.
If you stick to the “obvious” retailers, you’re safe – but never sure. Here’s the disclosure. It’s the same for every points promotion but I bet you’ve never heard of seen it:
Home Improvement Purchase means a net purchase made at a merchant that is classified, by such merchant, as hardware stores, home supply warehouse stores, building materials, hardware equipment and supplies, plumbing and heating equipment, lawn and garden supplies, paints and varnishes, contractors and other home improvement supplies under MCCs 0780, 1520, 1711, 1731, 1740, 1750, 1761, 1771, 1799, 5072, 5074, 5193, 5198, 5199, 5200, 5211, 5231, 5251, 5261, 5996 and 7692.
Costco is considered a discount club with MCC5300 –Walmart is typically MCC5310 (discount store) or MCC5311 (department store) but they may also have a code set up under MCC5541 (groceries) – but that’s unlikely. So no bonus points there for any promotion from anyone – ever.
You could:
-Call your card issuer and ask for the MCC code for a specific retailer – but I doubt you’d get it.
-Check your old statements in case they’ve had the same promotion in the past where you can see what qualified.
-If you get an annual summary of charges (not with Royal Westjet) that will give you the spending under specific categories and you’ll be sure those stores qualify
Or do what most everyone does: Get excited about the promotion and charge away and hope you might get the points in the MCC code crap shoot.
Lastly, if any bonus offer ever has you buying from a more expensive retailer just to get the points, you’re tripping over dime to pick up a penny. You REALLY need to read the “what are your points really worth” on page 139 of the Money Tools book.
AC refunds are here: As predicted, Air Canada will now fully reimburse your non-refundable flights in order to get the federal government bailout this week. Any tickets bought since February 1st, 2020 where you cancelled the flight because of the pandemic, or the flight was cancelled by Air Canada, are eligible. Just go to aircanada.com and follow the big link section at the top of the home page. You have until June 12th to do so. They are also offering a voucher, but that will not make you a free agent – take the money back on your credit card! Westjet will follow soon if and when they agree to their bailout plan.
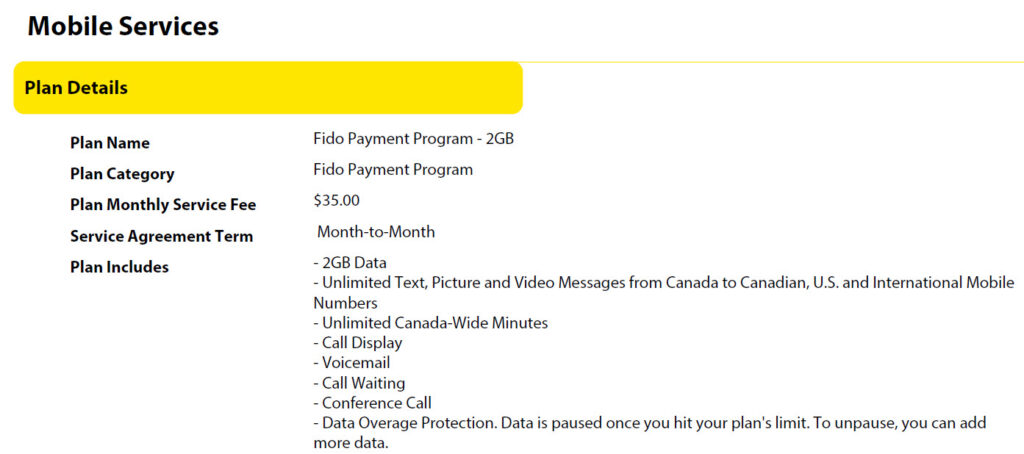
Cell rates: In response to Shaw entering the cell carrier market with their almost unlimited $25 plan if you are a Shaw customer, most other cell carriers have now dropped their rates. If you’re a free agent, make the call and simply tell them that you’re shopping around for a reduced monthly plan. If you’re not a free agent and locked in a contract – bad idea – and you’ll need to keep overpaying. If you deal with the big 3 of Rodgers, Telus or Bell you’ll likely also be out of luck. The main carriers (unlike their secondary providers) have a majority of customers and business clients that are not price sensitive).
My call was to FIDO (the secondary outlet of Rogers) and my plan went up 20 fold in data (2gig per month), added unlimited Canada-wide calling and free, full North America wide texting. and went from $45 down to $35! A $120 savings (23%) a year for a five-minute hassle-free call! PS: With Rodgers buying Shaw, the rate drops will likely stop in a year when the government approves the sale – and they will. Until then, enjoy the lower rates because of the competition in the industry!
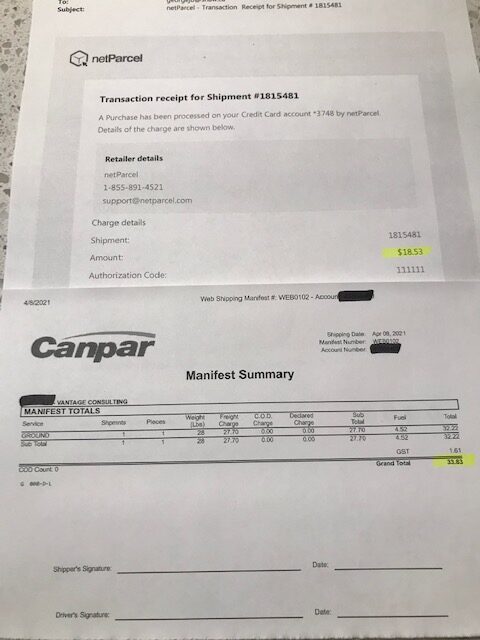
Netparcel.com update: Wow! We talked about this Canada Post parcel alternative a few weeks ago and a bunch of people have already tried it. I hadn’t when we talked about it – but did use it for the first time last week. It was a 28 pound parcel Edmonton to Kelowna. The site is super easy: Do the quote, set up an account, and a bunch of courier offers pop up. Mine was $18 from UPS. Enter the details and print the label I print my labels on normal paper and then tape it onto the parcel. The site, based on your postal code, then pulls up the closest 10 drop off depots or stores for you. Even with my Canpar Courier national book sellers association rates it was almost half the price!
(Note that it’ll be a different courier and different rate each time, even for the same parcel size and weight. This is dynamic pricing so you’ll get a different rate from different couriers depending on whether they want the business that day or that hour, how busy they are, where you’re shipping from and to, etc., based on supply and demand!!)
This picture pretty much encapsulates the state of many businesses. It’s a massive 15,000 sq ft. store in a so-called A mall. Those are newer malls, most with a large anchor tenant, and the malls that will survive. But this store is staffed by one person – guessing at $15 an hour, and sells nothing over $10. In the entire mall (Outlet Mall at the Edmonton Airport) there may have been 20 or 30 shoppers the three times I’ve been in there the last month.

In March, my company made $244 and it’s now month number 13. We’re now the second time around of no church services for Easter, no Grad celebrations, no spring plans, no Canada Day celebrations, no travel this summer, and no end in sight here in Canada.
Canada is currently (stats as of Friday April 2nd) 64th in vaccine procurement.
We’ve vaccinated 15.6 people per 100. In the U.S. it’s 45.9%. That’s more than triple our rate. The US, as of the end of next week, will vaccinate anyone over age 18 that wants it. They’ve had huge tents in mall parking lots across the country for months now.
And we have 1.8% of Canadians fully vaccinated. Less than two percent, while the U.S. is at 17.5% – TEN TIMES AS MUCH. When Ontario premier Ford called the federal efforts “a joke” he was right on the mark as of now.
I have a friend on Vancouver Island that is over age 65, with two pre-existing conditions, and he’s not even close to getting his vaccination. In a relatives’ nursing home in Calgary, there’s another outbreak because health care workers aren’t even vaccinated. Sorry, but I don’t see any of the national media in Ottawa asking any hard questions, or any signs that the federal government is exhibiting any signs of urgency.
California, one of the most cautious and locked-down states, is lifting all business related restrictions as of June 15th. Here in Canada, maybe middle-aged Canadians will get vaccinated starting in September. But that’s just another of many promises. If so, it will take until the end of the year to get most people vaccinated.
According to multiple websites, including ourworldindata.com, many third world countries are ahead of us in vaccinations to get back to some kind of “normal.” Even the most disorganized U.S. now has its act together. They vaccinated around 4 million people a day over the Easter long weekend. If you told me we did zero vaccinations, because it was a holiday weekend, I wouldn’t be surprised at all.
The government has extended the application time for the Canada Emergency Business Account loans, but not the criteria. So that doesn’t help at all. Plus, the original $40,000 loan has to be repaid by December 2022. But by the time we’re sort of back in business, that’ll be less than a year. What business will get back to 100% AND grow so quickly as to have an extra $30,000 net profit made inside of a year in order to re-pay the loan?
PLEASE: I, along with millions of Canadians, and tens of thousands of small businesses can’t go much longer at this rate.
Update: Sure enough, as we discussed, within two hours of talking about it, the U.S. CDC has issued a travel advisory for Canada because of our rising Covid numbers and lack of vaccinations…
In the last two years, Canada Post has increased their prices on parcel shipping to the point where I’m done. They’re so convenient and easy to get to, but at a massive cost.
If you’re a small business that ships something inside Canada or to the US every week, you HAVE to know the alternatives or you’re overspending literally thousands of dollars. Even if you’re just sending four or five parcels a year for presents, the alternates will save you at least a hundred bucks a year as well.
For individuals: Yesterday I discovered netparcel.com. The company gets bulk rates from courier companies that are insanely low. Last week I shipped a parcel to Calgary with Canada Post (0.72 kg) for $16.90. Netparcel would have been $8.67 – close to half the price for a tiny and light parcel! Their home page has a quick quote where you can get a courier rate inside of 10 seconds.

For small businesses: You HAVE to get away from Canada Post because those few thousand bucks of shipping costs you’ll save are pure profit. I sent 10 of my books to a great store on Harvey (in Kelowna) called Dare To Dream. Canada Post for the 2.6 pounds was $22 versus $10 almost anywhere else.

I also sell 8 of my books on Amazon in the US. That means that I have to ship inventory to Amazon quite frequently. The last parcel was 7.8 pounds and Canada Post to the US would have been $37. I paid $15, or 250% less through any company that does cross border shipping. These companies put US postage on your parcel. They then courier it across the border (to Sweetgrass Montana from here in Edmonton) and mail it at a US post office. No tax, no duty, no customs, no charge to get it across the border. So you’re sending it here in Canada as if you were across the border using the USPS. These companies give you a US address so you can also get incoming shipments from the US.
If you’re in the Okanagan, it appears that these companies aren’t there yet. If you find one, please let me know so I can share. The website for DYK is at: https://www2.dykpost.com/# and Net Parcel is at: https://netparcel.com/home.action
And finally, the blog from someone who has listed the different companies (in Canada) you may want to check: https://www.cindylouwho2.com/blog/2018/10/18/canada-post-alternatives-other-shipping-companies-in-canada


Hello George: We are at the renewal of our mortgage and are debating what would be the best move: prepay the mortgage or invest in our TFSA the amount of $12,000.00. We want to keep our monthly payment the same rather than taking the $130 lower payment.
We are both at or near retirement age and may want to sell our house in a couple of years to possibly be able to buy a family members’ house.
Part of my reply: You might get to buy that house and you might sell yours…that’s two BIG “if” questions without a today answer!
That means the $12k goes into the TFSA, or any savings account, to park it for the time being with easy access to it. There’s a saying that you can’t eat your home. In other words, when you need the money – for whatever reason – remortgaging takes time and is expensive. Even a home equity line of credit now has way more restrictions imposed by federal regulators.
If you put the money on the mortgage, you won’t have the down payment to buy the other one and will be forced to see yours super quickly (no matter what the price or market is at the time) to have the money for the 2nd purchase.
That’s assuming you don’t have the full amount in the TFSA to just write a cheque for the other home purchase and don’t have the massive income it’d take to get a mortgage on the 2nd one AND still have yours for a number of months until it sells. Likely zero chance of that with the Trudeau stress test restrictions! Besides, the $12k would “only” be a $50 principal reduction. $12,000/240 months plus a tiny bit of interest savings at such a low rate…Best have it ready and available!
Secondly, if you may be able to buy it and may or have to sell yours to make that work, you will have massive mortgage prepayment penalties to get out of your mortgage in year two or three out of five! It’d be over $10,000!
So I’d take a 3 year mortgage today to get to the point where the potential home purchase issue is resolved. Sure, I may cost you a little more on the renewal in three years, but it’d be way less than the massive penalties!
Thirdly, if you do get to buy it, do not NOY start at your bank. You’ll be turned down due to the Trudeau stress test. Immediately go to a good independent mortgage broker! You can find one by asking two of the top realtors in town who they use. They all do because their income depends on one that’s super sharp!
The above clip is from Modern Family when Mitch first discovers Costco. Even if you think you know Costco, there’s another whole new level you’ve never experienced.
Pack the car and make a trip to Edmonton – but a big truck would be better than a car! In two weeks (opening April 6th), the fourth Canadian Business Store opens in Edmonton (10310-186 Street – about 10 blocks from West Edmonton Mall), and it’s nothing like a normal Costco store!
I’ve been in a number of them in the U.S. and they’re quite overwhelming and very different. No bakery department, jewelry, clothing and the likes to take up space. But you will find over 2,000 items not stocked in regular Costco stores – and in more bulkier bulk form – much of it on pallets right on the floor, instead of on shelves.
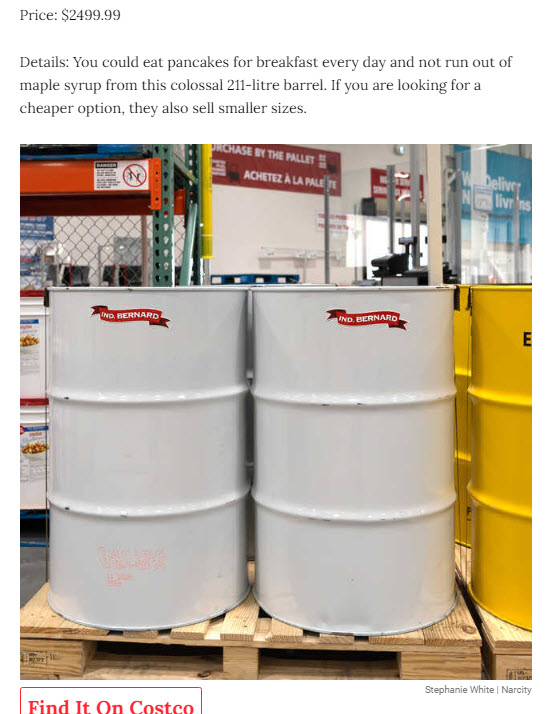
The reason you may need a truck is that the 211 litre drum of maple syrup ($2,500) probably won’t fit in the trunk of your car. If you can’t get your head around 211 litres, that’s one and a half full bathtubs. How about a 15 pound Toblerone (I love Toblerone, but I can’t be trusted with that much chocolate).
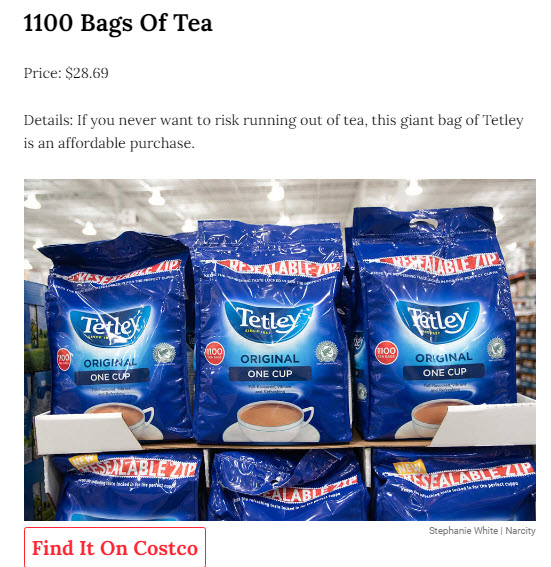
If you want to stock up on breakfast items for the next few years, I’d recommend the 25 pound jar of peanut butter ($64). Sure, it’ll take two people to lift it each morning, but think of the savings! And Tetley tea: A package of 1,100 tea bags for $28. That’s 2 ½ cents for your morning tea – and enough for the next three years. If you re-use a tea bag a second time (come on…be honest…) you’ll be good for six years. Let’s just hope your pantry for storage is as big as your trunk to get it all home! Edmonton may not be the City of Champions anymore, but now we’re certainly the City of Costco Business!
On the “Costco sad side,” they have now closed their in-store photo labs. It’s a casualty of digital and at-home printers. The reason it’s sad is that a simple 8×10 enlargement was $1.99. The best price I could find is now London Drugs at triple the price. Ouch! You can still order from Costco online – but with some pretty steep shipping rates.
And the “shame on you, Costco” is their new affiliation with an insurance company called Inova. They’re at inovainc.ca. I’ll post my experience with them in the next few weeks: A great online rate quote for my home insurance that turned out to be a totally legal scam, because the quote doubled when I called to place it.
If you’ve procrastinated making an RRSP or TSA contribution for 2020, you’ve got eight days left, but you might want to skip it this year.
What if I could get you a guaranteed and totally risk free return of 27%? Would that sound better than an RRSP or TSA this year? If you carry a credit card balance, like half of card holders, that’s exactly what you’ll get. Here’s an excerpt from the Money Tools book (page 144):
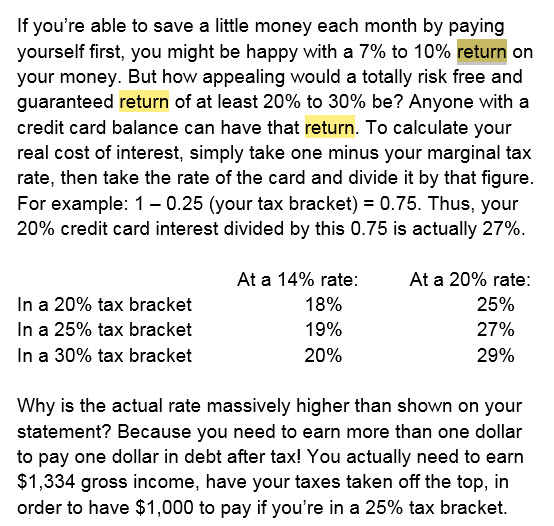
If you have a 10% line of credit, even in a pretty low 25% tax bracket, your real return will still be 13.3% if your priority is to pay that off.
What’s the bad news? You cannot do that if you want to save and become debt free at the same time. I’ve never seen anyone do it in 25 plus years, and you can read any number of Dave Ramsey books and find him confirming the same thing for just as many years.
We just don’t have enough money left over after paying all of our bills to make that last $200 bucks or so stretch to cover investing and paying off our debts. We can barely make the minimum payments each month. If you believe you can do both, it is the equivalent of attempting to defy the law of gravity. It won’t happen – but good luck to you. In two or three years, you’ll be exactly where you are today.
If you take three, four or five thousand dollars this week and put them into an RRSP or TSA while you’ve got high interest debt, such as credit cards or an overdraft, you’re making a big mistake.
If you’re going to borrow money for an RRSP contribution, I would suggest it’s an even bigger mistake because you’re adding to your debt and monthly payments. That’s exactly the opposite direction of where you should be going.
Yes, you should save and invest for your retirement. But a year or two of pressing the pause button is the only way to become debt free. If not, you’ll be another two or three years older, just as broke and just as poor. Before you make that pretty critical decision, read the Money Tools book chapter: Getting from here to debt freedom on page 207. You can get it from Mosaic Books on Bernard before you head to the bank to make your 2020 contribution…
(And since I always show my work: The $20 book, if you follow the two chapter sections, and what we talked about on the radio today, will end up saving you $1,530: You won’t have the 10% historical return of an investment over the next three years = out $993 compounded for three years. But you’ll have $3,000 less credit card debt at 27% (in 25% tax bracket) for a saving of $2,430. $2,430 less $993 = $1,437…excluding any tax refund – if any – if RRSP)