Category Archives: Blog

Happy New Year…But…

Sadly, as of last week, over 25 percent of resolutions have already gone by the wayside. But I have an idea and a way out of that: Think of January as a free trial month. You get that with some subscriptions, perhaps with a fitness club trial and other offers. So learn the lesson and start again on February 1st with your financial goals!

Make sure that your financial to-do and to-resolve list starts with something really simple, really short, but also really critical. It’s an entire chapter in the Money Tools book called: Do you have a half hour?

Yes, you do have it – but do you want to invest that half hour into getting some of your financial stuff in order for at least the coming year?

First thing is to have a coffee date with your partner if you are in a relationship. If you’re not on the same wave length – nothing else really matters. Talk about your financial goals and hurdles for at least this year.

Do you want a $10,000 vacation? If you don’t have it set aside, what’s the plan to save $800 a month if it’s next winter, or save $1,500 a month if it’s this summer.

Want to just charge it on a credit card? That’s your choice if you and your partner agree…but at a 20% rate it’ll be $20,000 in total price in four years. I think that’s a horrible idea, but it’s your choice IF you agree and IF you know what you’re getting into.

Is there one specific debt want to pay off? Do you agree it’s worth it and which one? How important is it to you two? What will you do or give up to achieve it?

If you’re a home owner, and your mortgage is coming up for renewal, are you planning to stay in town, in the home, in your job? What’s the longer term life plan…..because you don’t want to sign another five-year mortgage if you haven’t talked it through, or your penalties will be upwards of $20,000 if you change your mind!

Open a TFSA or RRSP: If you don’t have one – it takes less than half an hour with an online brokerage or your financial institution – that’s it. If your tax refund or other money comes in you have a way to invest it. If you don’t – that money is most likely going to leak out elsewhere.

Open an emergency savings account: You want a basic one week net pay to start. Not hooked to an ATM. But you first need the 15 minute to just open it and put 10 bucks in it. That’s a start – and the longest journey always starts with that first step!

It lets you get traction…because without it you’re not going anywhere…

A Few (Financial) Christmas Tips:

Can’t buy me love: That’s the title of a Beatles song, but so many grandparents attempt to do that with their over the top Christmas spending on grandkids. Kids on average play with their new toy for 20 minutes…then revert back to their current favourites. So you’d just be buying 20 minutes and you’re in competition with other gifts anyway.

Try spending less, but better, and test the 20-minute theory: Buy or get a BIG box (at least 4 or 5 feet square) and put their gift inside that massive box. Then time it: What do they play with and how long….you’ll see that it’s likely days with the box, versus minutes for the gift and that the box will get used for building a fort, or a ton of other creative and fun things for something you got for free, or cost you three bucks tops!

Don’t be selfish: Christmas isn’t about you gifting yourself. Commit to buying for yourself only after your January credit card statement. That way you’ve given yourself a short ‘time-out,’ and get to see the balance on your first post Christmas credit card. News flash: The average person underestimates their credit card spending by 20%. The day after you see you December statement, you can go nuts for yourself…but I’m betting you won’t….

Avoid Boxing Day shopping: Electronics on sale that day will have the Boxing day price as the regular price within months. Other things like clothing, shoes, etc. will also be on sale the entire month of January when retail sales are pretty dead. And do you really want to line up for an hour to save two bucks on wrapping paper? Sorry – that won’t change your financial life. Stay home, enjoy your family time, and not the line-up time. Boxing day stress just drains the Christmas spirit out of you in a hurry…

If you’re an adult kid over 18 and not living at home: Your parents do NOT want your PRESENTS that you likely can’t afford anyway. They want your PRESENCE. Believe me when I tell you that your presence, that quality time with your parents, is the best gift and at an affordable price if you get your priorities straight.

Merry Christmas!!

Breaking Down the “Free” Phone Offers

Almost every add, from every cell carrier, comes with the promo line of getting a “free” phone. Well…not so much. What it actually comes with, if you read the fine print, is a two year locked in contract at a BIG price.

Not paying for a new phone up front has no connection to “free” over those two years. Plus, all those contracts come with BIG early termination penalties. I would never sign one of those. For me, it’s always critical to stay being a free agent!

My current carrier is FIDO. They are the 2nd tier small sister of Rodgers. Because they just sent me this “free” offer, I’ll use them as an example. All other 2nd tier carriers will be about the same. All first-tier carriers like Telus, Bell, and Rodgers will be similar, just more expensive.

My cost is $40 a month because it’s an old month-to-month plan. New customers who bring their own phone can get it at $45 a month right now. The current promotion is double the 1 gb date to 2 gb, which is plenty if you do not live on your phone with youtube or watching movies. It’s unlimited texts and talk.

You can get a $15 a month plan if you bring your own phone. It has a tiny amount of data (250mb) enough to check stocks, short google searches, the weather, or hockey scores a few times a day. It’s unlimited texts but no call minutes – so you’ll pay 50 cents a minute.

That’s the baseline: $15 to $45 for no contract plans. Now let’s add the so-called “free” phone. In FIDO’s case, their promotion is the new iPhone 11 Pro. Pay for it up front and its $1,200. To get that you must sign an XL plan at $105 or more per month for two years. Yes, it comes with extra data, but $105 vs. $45 is $60 x 24 months or $1,440 for the phone.

Do the math on any plans with any carrier and it’ll take you less than a minute to see if your free is actually free…it isn’t – anywhere from anybody. There’s no such thing! How much you want to pay is up to you and your wallet.

Last week, I bought a new (new for me) iPhone 7. It still has six months of warranty and I paid $300. THAT lets me stay a free agent for at least three more years. I saved $800 over a new one, it’s in mint condition and saves me $60 a month not having a contract. $800 up front and $60 for the next three years is a total saving of $3,000! THAT is how you win at the cell game.

Oh, and I’ve mentioned them before: I get mine out of Winnipeg from TB Cellutions. Here’s their link on eBay Canada again:

http://stores.ebay.ca/TB-CELLUTIONS

Our Inevitable Recession

As we’ve talked about for more than a year, it’s coming – and at a really bad time for the average Canadian and the country.

This article from Diane Francis (in the National Post) describes it very well and it’s worth the read:

https://business.financialpost.com/diane-francis/diane-francis-the-inevitable-trudeau-recession-will-ravage-the-west-and-the-middle-class?utm_medium=Social&utm_source=Twitter&fbclid=IwAR0toF9y234wKmbP4b9xVrdjCfP_C-zbjbAMujPqDPxFiTIkCTw5oMZSsuk#Echobox=1575903591

Helping You This Christmas

It’s not just a US problem in having Amazon parcels stolen from your front door. But this might help: If you, or a family member, or neighbour have a lot of Amazon parcels dropped off, take the empty boxes from them.

While you’re cleaning your house for Christmas, take a bunch of stuff worthy of donation to the thrift stores. Take the stuff that isn’t donation worthy (in other words: your junk) and put it into the Amazon boxes and leave it outside your front door. If it’s stolen, it’s a win-win. You got rid of your junk and the thieves have their score…and maybe another chance to get caught! Talk about great recycling…

Want to help President Trump with a coverup? No, I’m not getting political…coverup as in Christmas wrapping paper!

This is guaranteed to make any potentially boring Christmas with relatives you may not be to fond off a whole lot more “interesting.”

For $35 you can buy Trump wrapping paper in three different styles and colours. One has snowflakes and a message of “I stand with Trump.”

Now THAT would….how do I put this…”liven up” your Christmas with the relatives.

Before you laugh or dismiss this, the National Republican Committee has sold over half a million dollars from this already! If you’re super excited about this AND want to save five bucks, you can get it on Trump’s campaign store: One 6 ft roll for $30….

Banks Want to Force You to Go Paperless

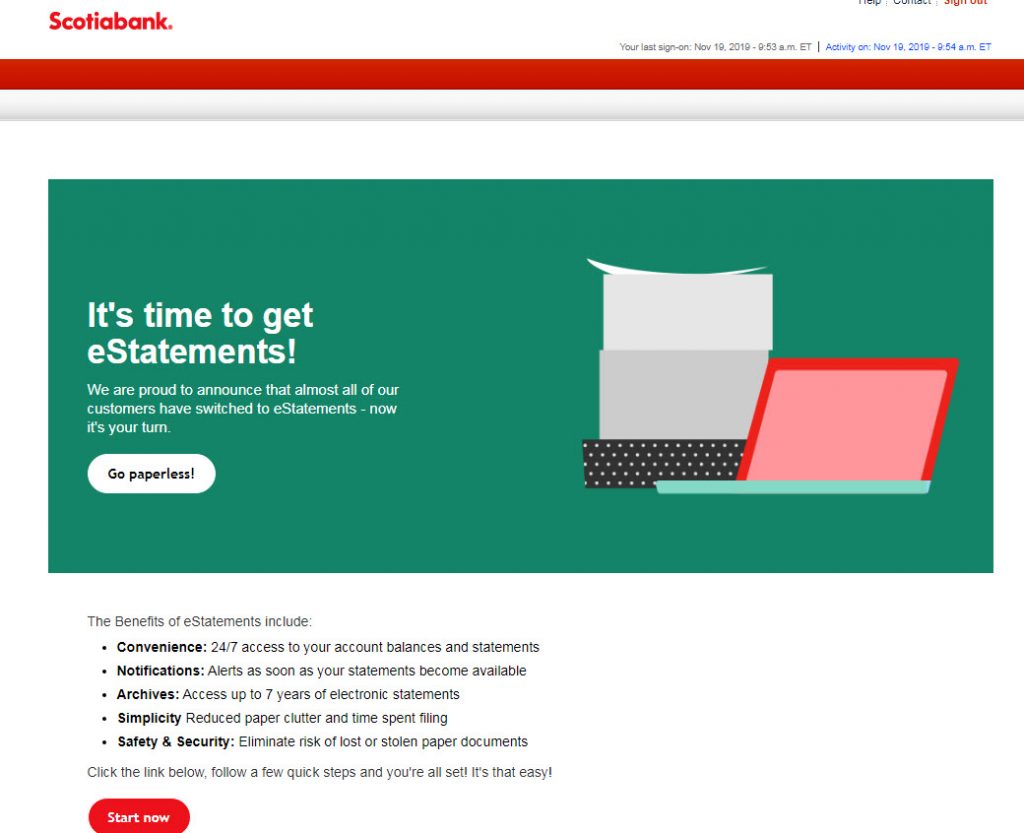
Two of the banks, including Scotia have now become more aggressive in bullying you to change from mailed statements to online and paperless. That’s your choice – not theirs!

On some of my accounts I want a paper statement. It massively increases the odds that you’ll actually scan it for inaccuracies or problems and I need to keep them for seven years anyway – so I’ll have to print them no matter what.

If you deal with Scotia, here’s what’s now coming up when you log in:

You’ll see that there’s no way to “x” out of it, click a “no thanks” or type in “leave me alone.” It forces you to click it and to go there. But no worries – the 2nd screen needs you to confirm you want to change to ‘online statements.’ At that page, just click on ‘accounts’ and get off that page and you’ve left your settings.

A Great and Extensive Cruise Review

I love, love, love cruises. My 20 plus cruises are always my favourites. But it’s not for everyone. You either love it or…not so much. If you’re the former, you can search for previous cruise stories over the years.

And here are two USA Today stories you’ll get lots of value from:

USA Today’s Cruise Lines, destinations, rankings, etc. https://travel.usnews.com/cruises/

And a great story on 31 insider secrets you should know to get the most value and enjoyment: https://www.usatoday.com/story/travel/cruises/2019/07/15/cruise-tips-secrets-and-hacks-cruise-lines-carnival-royal-caribbean/1738637001/

Tim Horton Troubles Continue

Yes, it’s still a financial-related segment, but today it’s about Tim’s. No, it’s not time yet to do a gofundme page for them, but they’re certainly not doing well. Do remember that Tim’s isn’t actually Canadian anymore. After their merger with Burger King, they’re owned by a Brazilian billionaire’s company called 3G Capital.

Last week, Tim’s announced the end of their CIBC Double Double Visa card that only started four years ago. I called it – all their hype didn’t translate to enough people getting their Visa at only 1% cashback. Sure, the press release (after days of meetings with CIBC I’m guessing) states it was mutual and both are moving on to bigger and better things. But that translates to: The CIBC can only market so many cards and this one isn’t enough volume or card holders to continue with. The same thing happened with RBC and their Mike Weir (the golfer) card.

If you have one, CIBC will automatically switch you to their Dividend Card. You may have seen this coming as CIBC has been sending $40 cash incentives way before the announcement to switch to another of their cards. Even if you don’t want that new one – it’s too late. So take that card and activate it. Your history will or should transfer over. If not, shame on the CIBC for dropping your credit score! Cancel it after a few month if you want and if you are NOT going to be looking to borrow for at least six months. If so, keep the card or your credit score will drop a bit!

And my predication number two is coming to pass: Their just released Rewards Card that gives you a free coffee after 7 purchases is going to get clawed back. That, according to their Canadian CEO on an investor conference call. Right now they’re losing money on it. About 50% of customers use the Reward card which costs them money – but it’s not increasing sales. They want to switch to ‘individual rewards.’ In other words: You’ll get rewards based on how much you deal with them.

Right now, their sales are down 1.4% in the last quarter. I’m partly responsible as my Tim’s trips are down by half: Their new dome lids leak a lot and after three times going home to get changed, I realized I was getting average coffee and frozen, then re-heated bagels with long lineups in stores because drive-throughs take priority and I could do better elsewhere. When the Rewards card changes – it’ll be the end of my love affair with Tim’s.

Lessons From Last Week’s Book Signing

Every time I do one of my (rare) book signing, I learn a lot. If it isn’t an insight, it’s what I need to explain better, more or differently. From last week at Mosaic Books, it was:

Making your teenager a millionaire: Your teenage relative won’t do it because you tell them and YOU know it’s guaranteed to work. They won’t listen to you and you can’t want it more for them than they want it for themselves.

A teenager isn’t likely to even listen to you. But maybe they’ll “get it” from the two page Money Tools book chapter. They have to read it and understand compounding works better the younger the person investing. You also have to remember that saving $9,300 is like asking you to come up with a few million bucks. Teenagers dream of $300 bucks and a BIG shopping trip to the mall next week. They don’t dream of $9,300 or anything past next month.

That’s where you come in: The chapter is two pages. When they ‘get it’ and work through the compounding math on their own where $9,300 becomes $18,600 in 7 years and $37,200 in 14 years without them doing anything at all – they’ll get committed. At that point you can also help. Maybe you can match what they save, maybe you can add 10 or 20% to what they save or whatever you can afford to boost the odds it’ll happen.

If you contribute anything at all, the deal should be that the investment account is in joint names. Your money is in there and then it’ll assure they don’t take out anything.

Not knowing this or doing this when I was early 20s or so is now one of the top 5 lifetime regrets of mine – for obvious reasons. And I’ll post the more detailed “how to and where to” invest again.

Spend the $20 on the book – at least make them read it and understand it – think about some seed money to get started or to keep going. THAT is starting a family legacy in ways nobody else does…